Diesel prices are approaching $6 a gallon, marking an all-time high just as American agriculture hits peak harvest season. The timing could not be worse for family farmers already operating on razor-thin margins.
The price spike is driven by three converging factors: escalating tensions in the Middle East, a halt to Russian fuel exports, and domestic inventories sitting at 20-year lows. In a normal farm year, you’d expect input cost warnings to reach commodity markets months in advance. But diesel reaches crisis levels overnight.
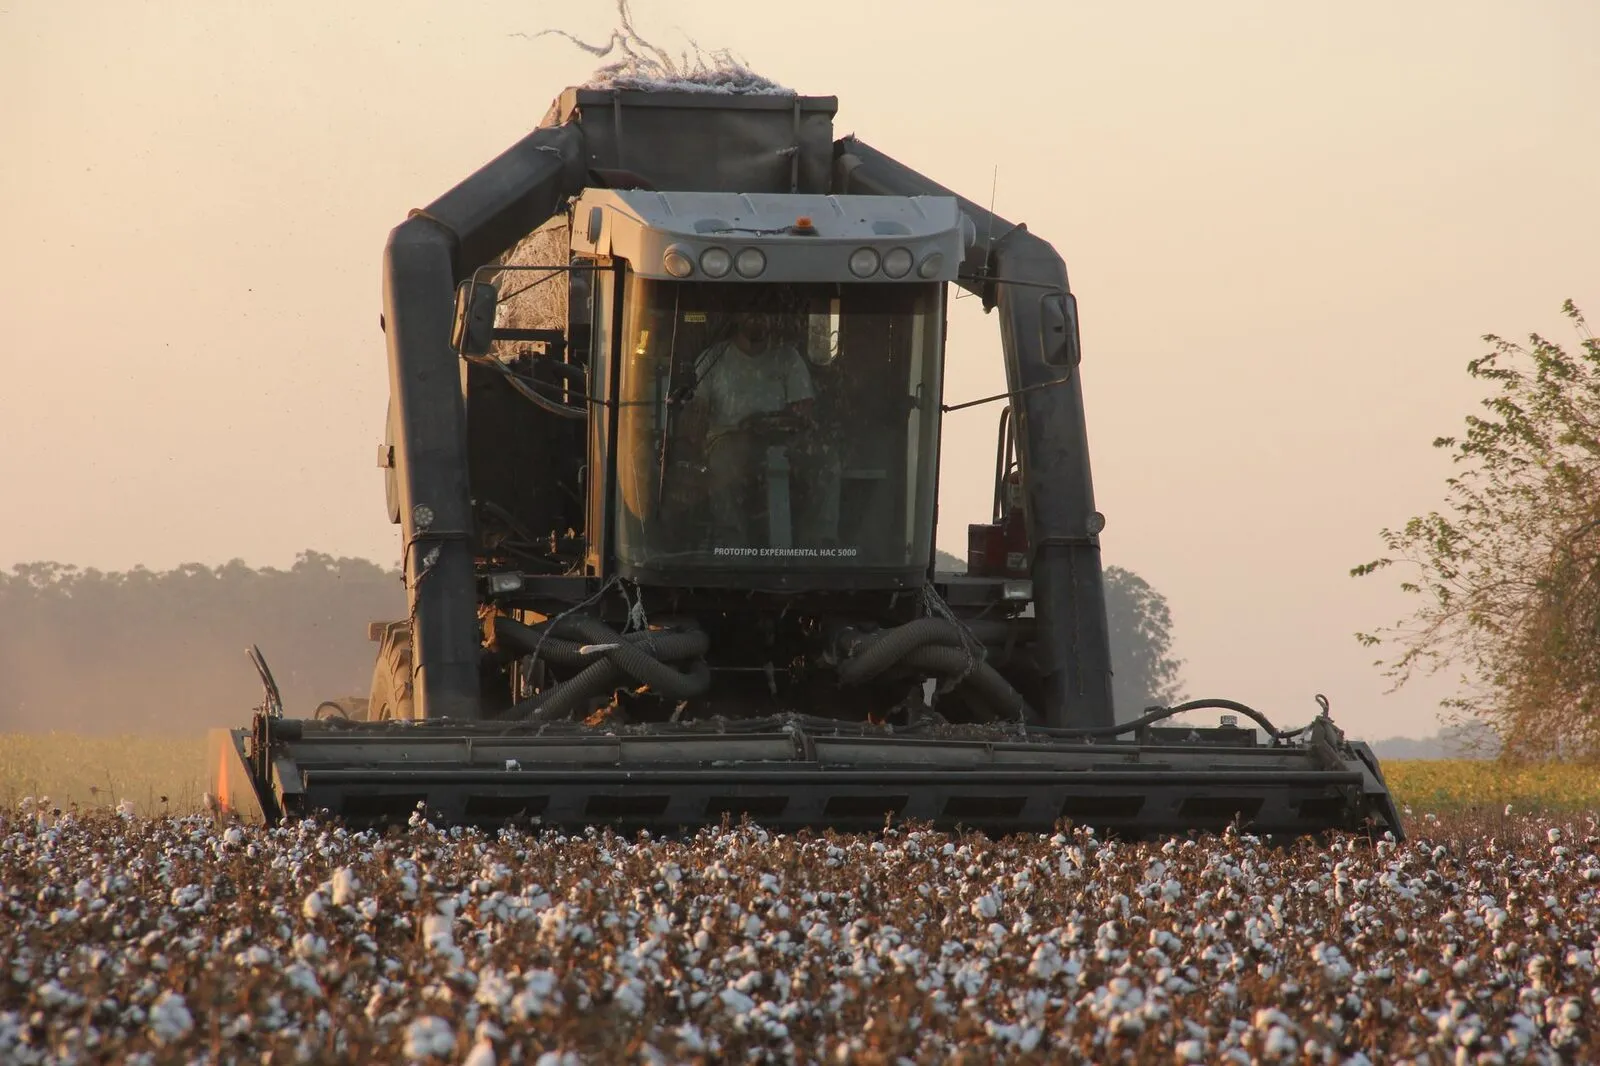
The economics are simple and brutal. A large modern combine uses roughly 3 to 5 gallons of diesel per acre harvested. A farmer running 500 acres of corn or soybeans burns 1,500 to 2,500 gallons during a standard harvest window. At $5.90 per gallon, that’s $8,850 to $14,750 in fuel cost for one crop on one machine. Add in tractors, grain carts, trucks, and backup equipment, and fuel becomes a line-item crisis for operations of any size.
For family farmers who already carry debt loads that have been climbing since the early 2020s, a sudden diesel spike doesn’t get absorbed by “efficiency” or “planning.” It comes out of margin. And for many operations, there’s no margin left to cut.
Farmers are already facing crushing debt amid volatile markets. Equipment costs locked in at current prices represent capital commitments made in a different fuel-price environment. A farmer who financed a $400,000 combine three years ago was budgeting on $2.50/gallon diesel. Operating that same machine at $5.90/gallon transforms the economics entirely.
The consolidation leverage here is significant. Large corporate farms and contract operations have already absorbed this price shock into their financial modeling. They’re running equipment debt across thousands of acres and holding fuel surcharge capacity in their processor or commodity marketing contracts. A family farm has no such buffer. Every dollar of unexpected fuel cost is a dollar borrowed or a dollar of unsold land equity pledged to operating credit.
When input costs rise faster than commodity prices, margins that looked viable in spring become underwater by fall. Soybeans are trading in the low $11s per bushel; corn is mid-$4s per bushel. Those prices were set before diesel touched $5.90. Farmers who locked in equipment and input budgets three months ago are now harvesting into a fuel-cost environment they didn’t budget for.
The diesel crisis also accelerates a shift in who can afford to own and operate agricultural land. Large-scale operations can absorb fuel surcharges. Contract harvesters serving multiple operations can pass costs to clients. But independent family farmers can’t. They harvest at a loss or they harvest less, both of which force a reckoning with lenders.
Young farmers and beginning growers are hit hardest. A beginning farmer leasing land or operating on borrowed capital to finance entry into agriculture now faces the worst input-cost environment in years. The business plan that looked viable in spring now looks like a money-losing proposition by fall. The decision to stay in farming or exit often hinges on fuel costs that spiked after the year’s commitments were already made.
Historically, USDA could use fuel price protection programs to buffer the worst fuel shocks, and commodity loan programs could offer a financial floor when input costs spiked. But policy has lagged far behind the speed and scale of consolidation in agriculture. A farmer facing a $5,000 to $15,000 unexpected fuel bill can’t wait for a government program that may or may not be funded or implemented by the time harvest is complete.
The geopolitical factors driving diesel prices are real and beyond the farm gate. Middle East conflict. Trade flows disrupted. Supply chains stressed. But from the perspective of a farmer sitting in a cab burning fuel to harvest a crop, the causes don’t matter. The cost is what’s real.
Diesel approaching $6 a gallon in September 2026 means harvest season for tens of thousands of family farms is happening at the worst possible input-price window. Farmers with liquidity and scale can push through. Farmers operating on thin margins or with recent debt loads face a choice: eat the fuel cost, which means losing money on the crop, or operate less equipment, which means a longer harvest that compounds other costs and risks.
The worst outcome is farms that survive this year but start next year with deeper debt, depleted credit, and a narrower margin for error. That’s how consolidation accelerates: not in a single catastrophic year, but over three or five years of input-cost spikes that eliminate the farms that can’t compound and rebuild.
Cross-links: